Best overall for one international trip: a single-trip travel medical plan. Best for frequent departures: an annual multi-trip plan. Best for a study-abroad term: a student travel medical plan. These are plan types, not insurer endorsements; the right policy depends on its written coverage for your destinations, dates and activities in 2026.
- For most travelers taking one trip, single-trip coverage is the best travel medical insurance plan type to compare first.
- Frequent travelers should compare annual multi-trip policies; students should check plans built for study abroad.
- MyAbroadMDs helps travelers find English-speaking doctors abroad, but its memberships are not insurance.
- Check medical exclusions, evacuation terms and trip-length limits in the actual policy before you buy.
Why this matters
An insurance policy answers a financial question: which eligible medical expenses will the insurer cover? Finding a doctor who speaks your language is a separate practical question. MyAbroadMDs offers subscription-based access to a personalized, curated directory of English-speaking doctors and healthcare providers across 100+ countries. It is not insurance, telehealth or a booking service.
That distinction matters before departure. You can have a policy and still need to identify a provider at your destination; you can find a provider and still have no insurance coverage for the visit. MyAbroadMDs is best for travelers who want an English-speaking provider directory alongside, not instead of, travel medical insurance. Its limitation is equally clear: a membership does not determine whether an insurer will pay a claim.
This 2026 guide ranks insurance categories by itinerary rather than naming a winning insurer. No specific insurer policy terms appear in the supplied information, so a provider-by-provider ranking would imply comparisons that cannot be supported. Use the categories to narrow your search, then use each policy document to make the final decision.
What makes the best travel medical insurance plan?
- Trip fit: Match the policy period to your departure and return dates. Check whether an annual policy limits the length of each individual trip.
- Destination fit: Confirm that every country on your itinerary is included. A stopover and a side trip still belong in that check.
- Medical terms: Read the definitions, limits, deductibles and exclusions for emergency treatment. Do not infer coverage from a plan name.
- Evacuation terms: Check when medical evacuation applies, who decides it is necessary and where the policy says you can be transported.
- Activity fit: Identify the activities on your itinerary and check their treatment in the policy wording. An appealing headline benefit does not override an exclusion.
- Help when you need it: Locate the insurer's assistance and claims instructions before you leave. Provider discovery and insurance assistance serve different purposes.
Choose by trip pattern first, then compare written policy terms. A single-trip policy that fits a two-week vacation is not automatically the right choice for a six-month study-abroad term. Likewise, an annual label does not tell you how long any one journey can last.
Best travel medical insurance plans at a glance
| Rank and plan type | Best for | Standout feature to evaluate | Key limitation to check |
|---|---|---|---|
| 1. Single-trip travel medical | One defined international trip | Dates matched to one itinerary | Coverage ends according to the policy period |
| 2. Annual multi-trip travel medical | Several separate trips | Repeat-trip coverage under one policy | Per-trip duration and destination restrictions |
| 3. Student travel medical | A study-abroad term | Fit with a school's requirements | Eligibility, program dates and side-trip terms |
| 4. Long-stay international health insurance | Extended residence abroad | Ongoing-care terms beyond a short trip | Not a substitute for checking travel-specific benefits |
The table is a route map, not a list of verified policies. Each row names a category to investigate in 2026. The insurer's current documents decide what you actually receive.
1. Single-trip travel medical: best for one defined trip
Best for: A traveler with one departure, known destinations and a return date. Single-trip travel medical insurance is the first category to compare for a vacation or other defined journey because you can assess it against one itinerary. The name alone does not establish which treatments, countries or activities are covered.
Imagine a two-week trip with one side excursion. Write down both destinations and all travel dates before comparing policies. Then read the coverage period, medical exclusions and assistance instructions; a summary page is no substitute for the policy wording.
Single-trip travel medical pros:
- Gives you a clear itinerary against which to check eligibility and coverage dates.
- Keeps the comparison focused on the destinations and activities you actually plan.
- Lets you inspect one trip's medical and evacuation terms without assuming future travel needs.
Single-trip travel medical cons:
- A later departure calls for a new coverage decision.
- A changed itinerary can create questions about dates, destinations or activities.
- The category name does not tell you whether existing conditions or particular activities are covered.
Single-trip travel medical verdict: Buy a policy in this category when one defined journey matches its written terms. Hold if your itinerary is still changing; settle the destinations and dates you need covered before selecting a policy.
For 2026 travel preparation, keep insurance and provider discovery on separate lines of your checklist. MyAbroadMDs can help you identify English-speaking healthcare providers through its membership directory, but it cannot replace the insurer's coverage or claims process. Check each service for the job it actually performs.
2. Annual multi-trip travel medical: best for repeat departures
Best for: A traveler expecting several separate international trips within the policy period. An annual multi-trip policy groups repeat departures under one policy, but the word annual does not mean every trip can last the entire year. The per-trip limit is one of the first terms to inspect.
Suppose your 2026 itinerary includes a short spring trip and a longer autumn trip. Compare each journey separately against the policy's maximum trip duration and destination rules. If the longer trip falls outside those terms, the convenience of one policy does not solve the coverage gap.
Annual multi-trip travel medical pros:
- Fits a travel pattern with multiple departures rather than one fixed journey.
- Gives you one set of policy documents to check across eligible trips.
- Prompts an early review of destinations and per-trip rules for the full itinerary.
Annual multi-trip travel medical cons:
- Individual-trip duration limits can rule out a longer journey.
- Destinations or activities can still fall outside the policy terms.
- A repeat-trip format is unnecessary if you have only one confirmed departure.
Annual multi-trip travel medical verdict: Buy when every planned trip fits the written per-trip and destination rules. Skip the annual format if you only need cover for one trip. Convenience is not a medical benefit, and it does not resolve an exclusion.
You should also separate a policy's assistance process from a doctor directory. MyAbroadMDs supports provider discovery across 100+ countries; it does not arrange an insurer's authorization, process claims or guarantee a particular provider is covered. Use the insurer's instructions for insurance decisions.
3. Student travel medical: best for a study-abroad term
Best for: A student whose travel is tied to a study-abroad program. Student travel medical plans are a category to compare with the school's stated insurance requirements and the student's actual itinerary. Do not treat a student-focused name as proof that a university accepts a policy.
A six-month semester can include travel before classes, breaks and a return journey. Check the precise coverage dates and destinations against all of those plans. If your school sets minimum benefits or other conditions, compare the policy document with the school's requirements before committing.
Student travel medical pros:
- Provides a category focused on a study-abroad itinerary.
- Creates a clear starting point for checking program requirements.
- Encourages review of travel outside the main study destination.
Student travel medical cons:
- Student eligibility rules differ by policy.
- A policy can fail a school's requirements despite its name.
- Side trips and activity exclusions require their own checks.
Student travel medical verdict: Buy a student policy only when the school accepts it and its written terms cover the student's planned dates, destinations and activities. Hold until you have the school's requirements in hand. They are a decision rule, not an optional extra.
MyAbroadMDs also offers memberships for study-abroad students, including Student Safe Abroad. That membership provides access to its personalized provider directory; it is not a student travel medical policy. Keep the membership and insurance decisions separate when preparing for departure in 2026.
4. Long-stay international health insurance: best for extended residence
Best for: Someone planning an extended stay abroad who needs to assess ongoing healthcare, not just medical needs during a short trip. International health insurance belongs in this comparison because a long residence can call for different policy terms than a defined vacation. It is not automatically the better choice for a traveler taking a brief trip.
Consider a 12-month stay rather than a series of short holidays. The relevant questions shift toward eligibility during residence, covered care, geographic scope and how the policy treats travel away from your main destination. Read those terms directly; different insurers can structure long-stay cover differently.
Long-stay international health insurance pros:
- Puts ongoing-care terms at the center of the comparison.
- Gives extended-stay travelers a category to assess against their residence plans.
- Prompts a close check of geographic scope when travel continues during the stay.
Long-stay international health insurance cons:
- It can be a poor fit for one short, defined trip.
- Travel-specific benefits cannot be assumed from health coverage alone.
- Residence and eligibility rules require careful reading.
Long-stay international health insurance verdict: Buy only if the policy terms fit your extended-stay needs and destinations. Skip it as a default for a short vacation. A longer policy period does not, by itself, establish better travel medical coverage.
How these categories were ranked
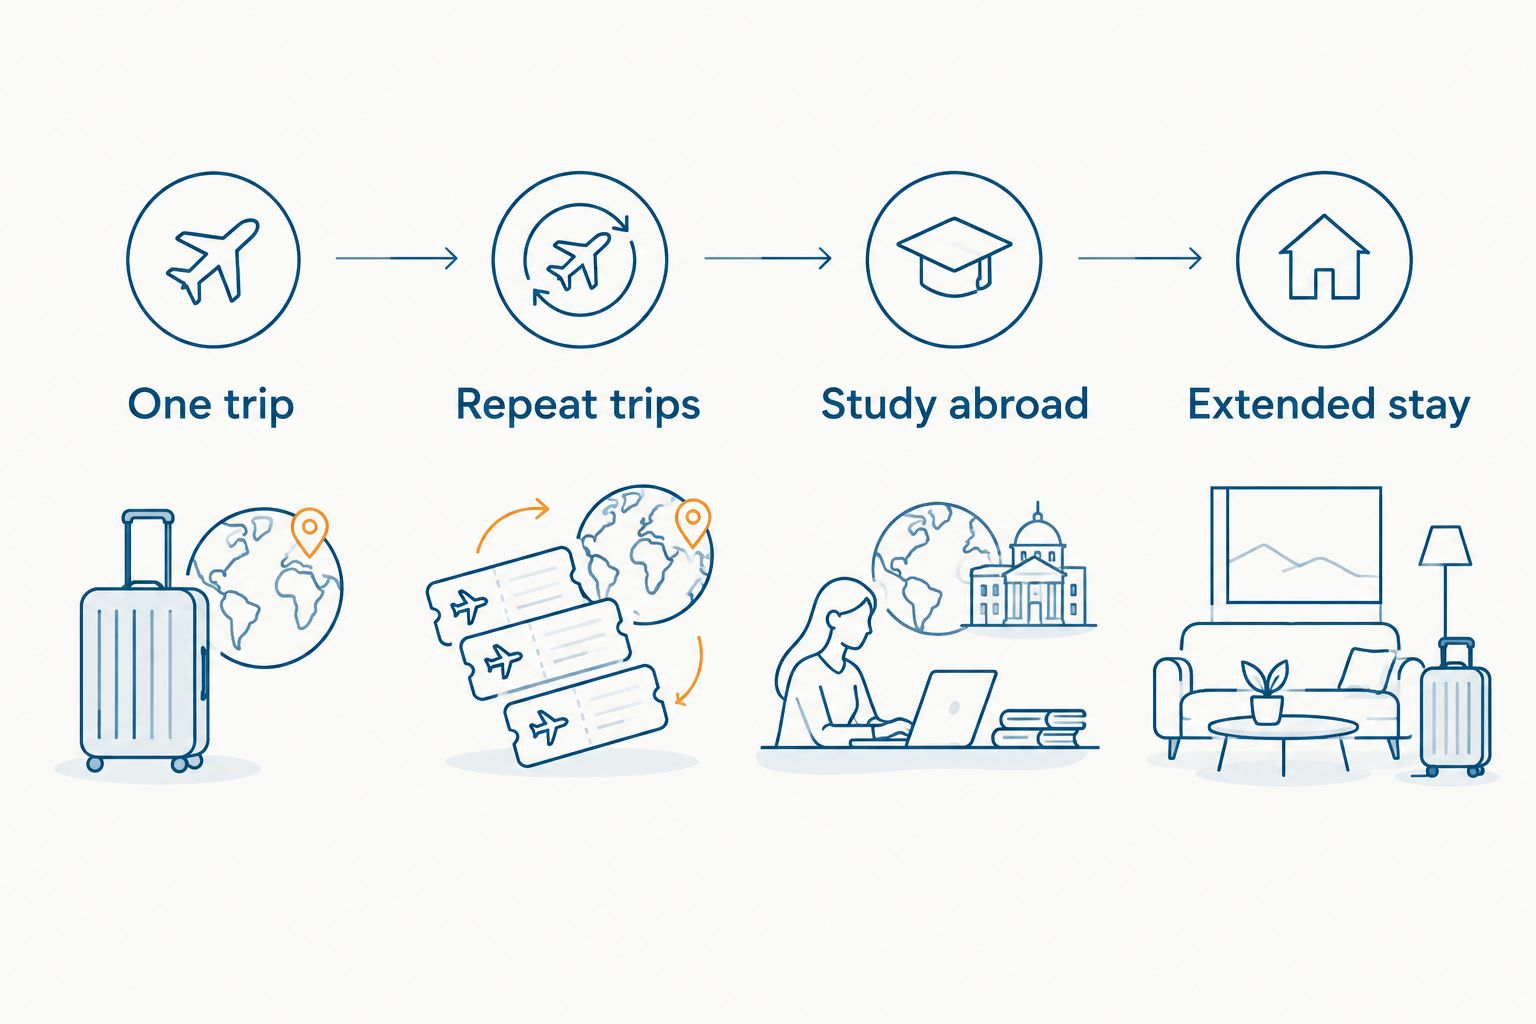
The order answers a common itinerary question: where should you start if you need medical coverage for international travel in 2026? A single defined trip comes first, followed by repeat departures, a study-abroad term and extended residence. These are different use cases, not claims that one insurer outperforms another.
To compare actual policies within your category, put the written terms side by side. Check coverage dates, destinations, medical limits, exclusions, evacuation wording and assistance instructions. If a clause is unclear, ask the insurer to explain it before purchase and keep its response with your travel documents.
No category removes the need to read the policy. The best travel medical insurance plan for travelers is the one whose written terms fit the complete itinerary. A recognizable plan name cannot make an excluded destination, activity or period eligible.
Which travel medical insurance plan should you choose?
Start with single-trip travel medical insurance if you have one defined international journey. Compare annual multi-trip cover if you have several departures and every trip fits its individual-trip rules. Students should put the school's requirements beside a student policy; extended-stay travelers should compare international health insurance against their need for ongoing care.
Once you have a policy category, finish the 2026 departure checklist with two separate checks: how to contact the insurer and how to locate a suitable healthcare provider. MyAbroadMDs addresses the second task through its curated English-speaking provider directory across 100+ countries. It does not supply the insurance policy, arrange appointments or deliver medical consultations.
FAQ
What are the best travel medical insurance plans for travelers in 2026?
For one defined trip, compare single-trip travel medical policies first. For repeat departures, study abroad or extended residence, compare the corresponding plan category against your dates, destinations and written coverage terms.
Is annual multi-trip insurance better than single-trip insurance?
Annual multi-trip insurance is the better category to investigate when you have several separate trips that meet its per-trip rules. Single-trip insurance is the clearer starting point for one defined journey.
What should study-abroad students check before choosing insurance?
Study-abroad students should check their school's insurance requirements against the policy's eligibility, dates, destinations and benefits. A student plan name does not establish school acceptance.
Does travel medical insurance cover every activity abroad?
No plan should be assumed to cover every activity. Check the policy's activity definitions and exclusions against what you intend to do.
Is MyAbroadMDs travel medical insurance?
No. MyAbroadMDs sells memberships that provide access to a personalized directory of English-speaking doctors and healthcare providers; it does not provide insurance, telehealth or a booking service.
Can I use a doctor directory instead of travel medical insurance?
No. A doctor directory helps you identify providers, while insurance terms determine eligible medical expenses and claims procedures. The two address different parts of travel preparation.
When should I check my policy's destination rules?
Check destination rules before choosing a policy and again if your itinerary changes. Include planned side trips when comparing the written terms.
One last thing
A side trip is easy to overlook when the main destination dominates your plans. Put every destination and activity on your 2026 itinerary in front of you before comparing policy wording. Choose the insurance for coverage; use a provider directory for finding care. Neither one silently does the other's job.